Individual Health Insurance

Best Health Insurance Plans in India Expert Comparison Guide
BimaStreet Blogs, Health insurance

Best Health Insurance Plans in India: Expert Comparison Guide

As the medical inflation in India grows higher with time, selecting the Best Health Insurance Plans in India is becoming increasingly crucial. In any case, a minimum of a few lakhs are required for hospitalised patients Therefore health comes under the purview of financial planning Despite all of this choice, dozens of insurers and hundreds of plans can make it difficult to pick the best policy for you The best health insurance plan comes with more than just affordability most buyers compare only premiums. Claim settlement ratio, network of hospitals, waiting period, room rent limits, restoration benefits and customer support are some factors that help assess the value for a policy In this expert comparison guide, you will get to know what the Best Health Insurance Plans in India are, how to compare features and pick the right policy that fits your needs. What Makes the Best Health Insurance Plan? Key Features to Compare Here are some of the key points you should assess while comparing the Best Health Insurance Plans in India. High sum insured Cashless hospitalization Large network of hospitals Strong claim settlement record No room rent restrictions Coverage for day-care procedures Pre and post-hospitalization expenses Restoration of the sum insured Annual health check-ups Lifetime renewability A wide-ranging policy needs to offer general coverage instead of just the cheapest premium Top Health Insurance Plans in India Popular Plans Worth Comparing A number of our plans are perennial favorites due to their great features and all-around value. Independent comparisons frequently highlight Bimastreet By Amaze Insurance Brokers Pvt Ltd HDFC ERGO Optima Secure+ Care Supreme Aditya Birla Activ One MAX Niva Bupa ReAssure Platinum SBI Super Health Platinum Infinite There is no one best plan for everyone. The right choice depends on your age, medical history, finances and healthcare needs. Compare Coverage Instead of Premium Bigger Protection Is More Important Avoid opting for a policy only because it comes with the least premium Compare Hospitalization coverage ICU expenses Ambulance charges Day-care procedures Organ donor expenses AYUSH treatment (where covered) Domiciliary hospitalization Mental health coverage (if included) A Slightly increase in premiums can offer a lot better protection Check the Claim Settlement Record Reliability Matters This outlines the efficiency of an insurer in settling genuine claims. While this can not be the only consideration, it always feels better to have an insurer that has a track record of good claim settlement performance to give you peace of mind during medical emergencies Also, compare customer service, complaints and claim processing efficiency Evaluate the Network Hospital List Cashless Treatment Is Essential No monetary burden on hospitalization with cashless treatment Choose an insurer that offers A large network of hospitals Good hospitals near your residence Easy cashless claim process Fast authorization The greater the number of providers within your network, the smoother your treatment experience Understand Waiting Periods Read the Policy Carefully Waiting period for illness Most of the health insurance policies have specific waiting time before one can claim for some conditions These may include: Initial waiting period Pre-existing diseases Specific illnesses Maternity benefits You may dodge potential claim shock in the future by comparing waiting periods before purchase Look for Restoration Benefits Extra Protection After a Claim Most of the contemporary health insurance plans provide you an automatic restore of your sum assured after it has been completely exhausted as a result from the availing act. This facility may be highly beneficial if there are multiple hospitalizations during the same policy year Consider Your Family’s Needs One Plan Doesn’t Fit Everyone The Best Health Insurance Plans in India vary depending on who needs coverage Choose wisely if you are: A young professional A married couple Parents with children Senior citizens Someone with pre-existing diseases Make sure to always choose a plan according to your present and future medical needs Common Mistakes to Avoid Don’t Make These Buying Errors Avoid these mistakes Buying only because of a low premium. Ignoring waiting periods. Choosing inadequate coverage. Not checking room rent limits. Forgetting to compare network hospitals. Hiding pre-existing diseases. Ignoring policy exclusions. A close comparison today can save a financial headache tomorrow Frequently Asked Questions Which is the best health insurance plan in India? Not everybody has a plan that works for them. The best plan for you is determined by your age, number of family members, budget, medical history, and the hospitals where you want to get treated How much health insurance coverage should I buy? Most planners advise for a sum assured which at least covers major hospitalisation expenses in your city, given medical inflation Should I choose the cheapest policy? No, Never. Instead of focussing on premium, compare only coverage, claim settlement ratio, waiting periods, exclusions and network hospitals Conclusion Selection from Best Health Insurance Plans in India involves lots of research and comparative study. Instead of going for a policy based on price only, consider full coverage, claim settlement records, network hospitals, waiting periods restoration benefits and customer services A good health insurance policy is not only about protecting financially but also offers individuals peace of mind during difficult times A careful comparison of the plans and understanding a specific family member’s needs can not only safeguard your hard-earned finances but will also ensure you receive the medical treatment needed at every step At BimaStreet, we believe that the right guidance is just as important as the right policy. When you understand what insurance advisors look for before recommending a plan, you’re in a much better position to choose health insurance that protects your family today and in the years ahead
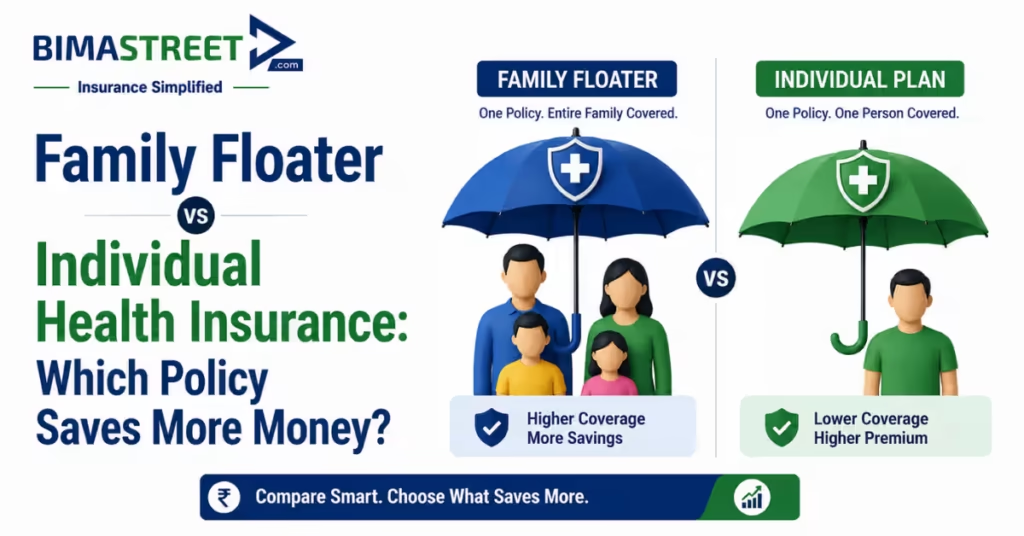
Family Floater vs Individual Health Insurance Which Policy Saves More Money
BimaStreet Blogs, Health insurance

Family Floater vs Individual Health Insurance: Which Policy Saves More Money?

It is essential to select the best health insurance policy for you and your family as it will be one of the most significant financial choices you will make in your life ahead As annually more and more health care costs are escalating, so having sufficient wellbeing insurance coverage is not a choice but rather a necessity. But, most of them face a challenge between Family Floater vs Individual Health Insurance. Finally, the other question is Whether to buy one policy for the family or each family member should be on a separate health insurance plan? The response is determined by your family size, age, medical history and economic goals This guide breaks down Family Floater vs Individual Health Insurance, how each of those work, their pros and cons, and which option can save you the money in the long run What Is Family Floater Health Insurance? One Policy for the Entire Family A Family Floater Health Insurance policy comes with a common sum insured which can be utilized by all members covered under the same policy. A family floater plan (say a ₹10 lakh plan that covers you, your spouse and two children) allows any of the insured to avail of cover as and when he/she is hospitalized till the limit is exhausted This policy suits young families, as the chance that several family members would require hospitalization at the same time is minimal. What Is Individual Health Insurance? Separate Coverage for Every Person Individual Health Insurance A separate sum insured is provided for each insured person. If there are four family members with ₹5 lakh policy each, all four will receive a cover amount of ₹5 lakh each When a claim is made by one party, it doesn’t decrease the coverage available to any other policyholder. This alternative is especially useful for those families who have parents or any other member in their family with prior ailments   Family Floater vs Individual Health Insurance: Key Differences Understanding the Main Comparison Key Points to Consider While Validating Family Floater vs Individual Health Insurance: Coverage structure Premium cost Number of family members Age of insured persons Medical history Claim flexibility Long-term affordability This helps to understand the differences and pick a policy suitable to your health care needs. Benefits of Family Floater Health Insurance Why Many Young Families Prefer It Advantages of a family floater plan are as follows: Family plan with single premium Less pricey than buying multiple separate policies. Easier policy management. Cumulative sum insured for family members. Convenient renewals If your family members are generally healthy, a family floater policy can provide excellent value for money Benefits of Individual Health Insurance Why Separate Policies Can Be Better There are also unique benefits to individual plans: Individual coverage for each insured person. Others are not influenced by the claim made by one person. Better for senior citizens. Best for Chronic Illness You have more freedom regarding your coverage amounts Other changes in cover and multi-policies often demand individual policies for families to meet their healthcare needs Which Policy Saves More Money? It Depends on Your Family’s Needs Family Floater Vs Individual Health Insurance: Which One Do You Need? A Family Floater policy is likely to help save you more if: You are a young couple. You have small children. There are no significant background diseases in your family. Everyone is generally healthy If Individual Health Insurance is a better investment, You have elderly parents. A relative regularly incurs medical expenses. Multiple members may require hospitalization. You want each of them given separate protection A bad policy choice either results in unnecessarily high premiums or underinsurance Factors to Consider Before Buying Health Insurance Make an Informed Decision Before purchasing any policy, evaluate Age of each family member. Existing medical conditions. Number of dependents. Annual healthcare expenses. Waiting periods. Hospital network. Claim settlement ratio. Room rent limits. Day-care procedures. Policy exclusions This move allows you to make a more informed financial decision by weighing these features against each other Common Mistakes to Avoid Don’t Make These Health Insurance Errors Avoid these common mistakes: Choosing the cheapest premium only. Ignoring waiting periods. Not reading policy exclusions. Buying insufficient coverage. Forgetting annual renewals. Not comparing different insurers. Delaying health insurance purchase. The right policy today can save you a world of financial heartache tomorrow Frequently Asked Questions Is Family Floater cheaper than Individual Health Insurance? Generally, yes. Family floater plans tend to be cheaper than independent policies for each member of the family, particularly for young and healthy families Can senior citizens be included in a Family Floater policy? Yes, but if parents are added it could more than double the premium. In many instances, buying separate individual plans for seniors is likely to be a better solution Can I switch from Family Floater to Individual Health Insurance? Yes. Several insurers also allow policy holders to switch from a family floater plan to an individual policy as per their terms Conclusion Family Floater vs Individual Health Insurance not about finding the better of the two but selecting what is best for your family. If you have a young and healthy family, you can get significant cover via a family floater plan but will be charged less in premium. If your household contains an aging parent or high-risk individuals, on the other hand, individual health insurance might prove considerably more beneficial in a long-term financial perspective You may also compare the various features, limits of coverage, waiting periods, eligible hospital network, settlement records for claims before arriving at a decision One cannot emphasize the importance of investing in good health insurance here as financially protecting your family today will lead to peace of mind tomorrow. At BimaStreet, we believe every family deserves coverage that matches their unique needs. Understanding how much health insurance coverage you really need is the first step towards making a confident and informed insurance decision.

Contact Details

Support mail:

care@bimastreet.com

Claim mail:

claim@bimastreet.com

For Other Query:

info@bimastreet.com

Phone Number:

(+91)9391009482/84/89

BIMASTREET is the online insurance platform of Amaze insurance brokers pvt ltd

Corporate Office :- #403, THE LEGEND, Metro Pillar C1338, Motilal Nehru Nagar, Begumpet, Hyderabad – 500016

Regd Office: – Ground Floor, Villa No.10, Richmond Villas, Near Glendale International School, Hydershakote, Hyderabad-500086.

Website Approved By IRDAI(Govt. of india)
ISNP Ref: IRDAI/INT/ISNP/2021/79
IRDA License Number: 549
Licensed on: 24/02/2025
Valid Upto: 23/02/2028

Disclaimer: Disclaimer: Insurance is the subject matter of solicitation. Visitors are hereby informed that their information submitted on the website may be shared with insurers. The product information for comparison displayed on this website is of the insurers with whom our company has an agreement. Product information is authentic and solely based on the information received from the Insurer. The information provided on this website/page is for information purpose only. Bimastreet.com does not in any form or manner endorse the information so provided on the website and strives to provide factual and unbiased information to customers to assist in making informed insurance choices.

Scroll to Top