Purchasing a health insurance policy is one of the wisest financial decisions you can make now more than ever, with medical expenses mounting across India.
But suppose you have an existing disease like diabetes, high blood pressure, asthma or thyroid disorders or heart diseases,
and this leads you to ask yourself whether the health insurance policy will cover you
And this is where having a proper awareness of Pre Existing Diseases Health Insurance comes in
Some people think that if you have a previous medical condition, insurers will deny anyone who applies,
while others feel as though every doctor bill is covered right away after purchasing a policy
In actuality, neither of these is entirely true
However, many health insurance companies do provide coverage against pre existing diseases but impose a waiting period and terms to the policy
The better you know these rules before getting a policy, the less likely your claim will be rejected and you might not end up with a nasty surprise on your out-lay.
In this guide, we will explain how Pre Existing Diseases Health Insurance works, what is covered and not covered, and how to choose the right policy based on your health requirements
What Are Pre Existing Diseases?
Understanding the Definition
A pre existing disease is an illness, injury or medical condition that a person has been diagnosed with or treated for before the purchase of a health insurance policy
Common examples include:
- Diabetes
- High blood pressure (Hypertension)
- Asthma
- Thyroid disorders
- Heart disease
- Kidney disease
- Arthritis
- Cancer (depending on medical history)
- High cholesterol
- Chronic liver disease
When obtaining a policy, you have to truthfully tell insurance companies about these conditions
Does Health Insurance Cover Pre Existing Diseases?
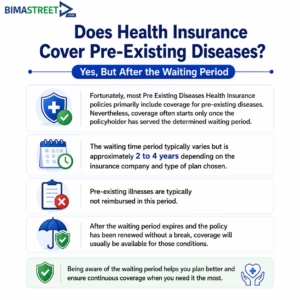
Yes But After the Waiting Period
Fortunately, most Pre Existing Diseases Health Insurance policies primarily include coverage for pre existing diseases.
Nevertheless, coverage often starts only once the policyholder has served the determined waiting period.
The waiting time period typically varies but is approximately 2 to 4 years depending on the insurance company and type of plan chosen
Pre existing illnesses are typically not reimbursed in this period.
After the waiting period expires and the policy has been renewed without a break, coverage will usually be available for those conditions
Why Do Insurance Companies Have Waiting Periods?
Protecting the Insurance System
To keep health insurance companies from misusing this feature, waiting periods are used to ensure fairness
Absent waiting periods, individuals could buy insurance after being diagnosed with a costly illness and habitually file claims just afterward
Waiting periods help insurers:
- Reduce fraudulent claims.
- Maintain affordable premiums.
- Ensure long-term policy sustainability.
- Protect genuine policyholders
What Is Covered Under Pre Existing Diseases Health Insurance?
Coverage After the Waiting Period
After the specified waiting period, a number of policies offer coverage for qualified expenses associated with pre existing conditions such as:
- Hospitalization expenses
- Doctor consultation charges
- Surgery costs
- ICU expenses
- Medicines during hospitalization
- Diagnostic tests
- Day-care procedures (if covered)
- Cashless treatment at network hospitals (where applicable)
This is determined by the finer print of a certain policy and any exclusions
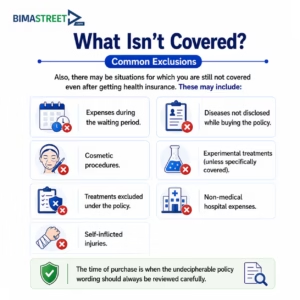
What Isn’t Covered?
Common Exclusions
Also, there may be situations for which you are still not covered even after getting health insurance
These may include:
- Expenses during the waiting period.
- Diseases not disclosed while buying the policy.
- Cosmetic procedures.
- Experimental treatments (unless specifically covered).
- Treatments excluded under the policy.
- Non-medical hospital expenses.
- Self-inflicted injuries
The time of purchase is when the undecipherable policy wording should always be reviewed carefully
Why Full Disclosure Is Important
Never Hide Your Medical History
There are some buyers who conceal pre existing health conditions to earn lower premiums or gain lesser scrutiny
This can be a costly mistake.
While processing claims, insurance companies crosscheck medical records.
If they find a pre existing disease was intentionally concealed, they may deny the claim or even cancel the policy
Always disclose:
- Existing illnesses
- Previous surgeries
- Ongoing medications
- Medical history
- Previous hospitalizations
This facilitates less hassle in the settlements of claims
Tips to Choose the Right Health Insurance Policy
Compare Before You Buy
While comparing the policy for pre existing diseases, consider
- Waiting period duration
- Sum insured
- Premium
- Network hospitals
- Cashless treatment availability
- Claim settlement ratio
- Co-payment clauses
- Disease-specific exclusions
- Renewal benefits
Carefully patching up your policy helps you find the best coverage that would suit your needs.
Common Mistakes to Avoid
Protect Your Future Claims
Avoid these common mistakes:
- Buying insurance only after serious illness.
- Hiding pre-existing diseases.
- Ignoring waiting periods.
- Choosing insufficient coverage.
- Not renewing the policy on time.
- Focusing only on low premiums
If it gets done today, it will be a lot easier to deal with these financial bumps in the road should they come in the future
Frequently Asked Questions
Can I buy health insurance if I have diabetes?
Yes. While nearly all insurers cover diabetes, there is generally a waiting period before you can claim for any conditions related to your injury or illness
Will my claim be rejected if I have a pre-existing disease?
Not necessarily. If you registered the condition truthfully and fulfilled any relevant waiting period, qualified claims are usually covered in accordance with policy terms
Can I reduce the waiting period?
Others provide waiting period-reducing riders or plans. Do not settle on a policy before comparing.
Conclusion
Pre Existing Diseases Health Insurance becomes necessary if one already has a prior medical ailment or is seeking full-fledged health cover for any point in future
Although pre existing diseases are covered by the majority of insurers, this coverage is usually not available during the agreed waiting period.
A good policy can help you claim without the hassle, but getting it is just the start with proper disclosure of your entire medical history,
understanding of waiting periods and exclusions from cover and renewal of your policy without breaks By planning ahead
you and your family can avoid the rising costs of health services while gaining peace of mind
At BimaStreet, we believe that the right guidance is just as important as the right policy.
When you understand what insurance advisors look for before recommending a plan, you’re in a much better position to choose health insurance that protects your family today and in the years ahead