Purchasing health insurance is meant to act as a support for you and your family, especially during medical emergencies.
But one of the major irritations that policyholders have to face is having their Health Insurance Claim Rejection
However, claim rejection is not a case of health insurance not working in most cases.
It happens because critical policy conditions were misunderstood, ignored or completely missed
Fortunately, as long as you know a few things and take the time to prepare, most claim denials can be prevented.
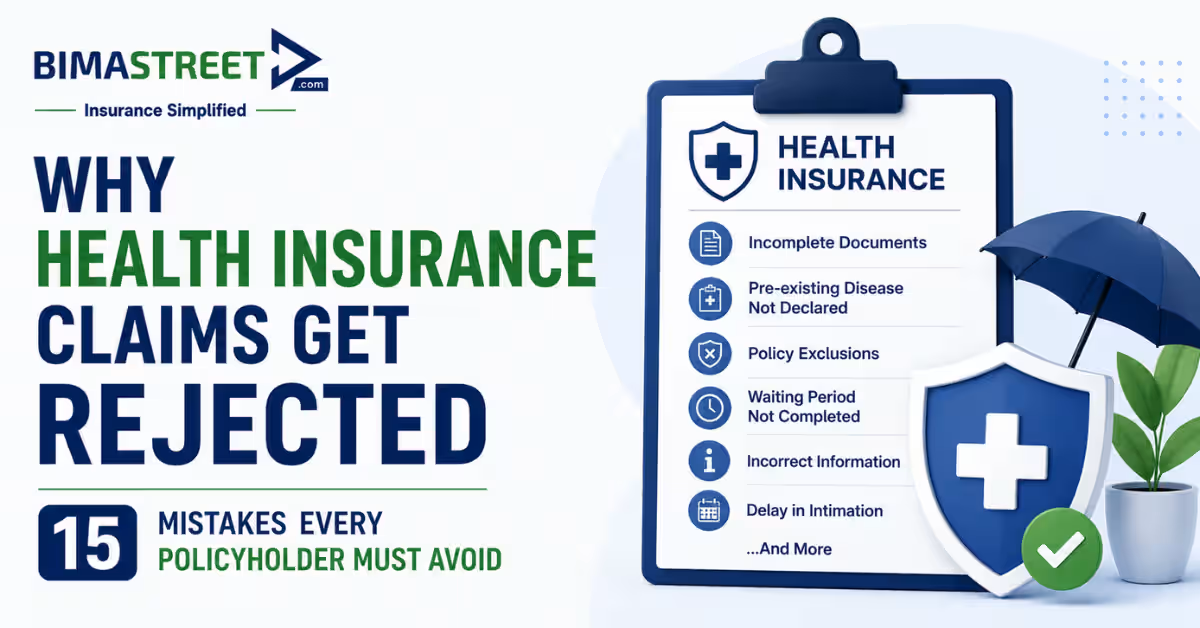
By knowing the 12 common mistakes that policyholders make you will immediately enhance your odds of a smoother claims process
Let’s look at the most common reasons behind health insurance claim rejection and how to avoid them
Why Do Health Insurance Claims Get Rejected?
A health insurance claim is evaluated according to the policy meanings and terms.
The claim might be denied or settled partially since it is not covered under the policy after all
Proper knowledge about the Health claim rejection reason may assist the policyholder in making the right call during an emergency and avoid facing a shocking event
Hiding Pre-Existing Medical Conditions
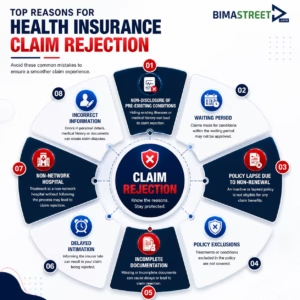
Non-disclosure of existing medical conditions is one of the top reasons for Health Insurance Claim Rejection
Always disclose all health history, ongoing treatments and prior illnesses when purchasing a policy.
Overall, being honest while purchasing a policy goes a long way in leading to an easier claim processing later.
Providing Incorrect Information
Even a minor error in personal information can trouble you at the time of claim assessment
Always verify
- Name
- Age
- Contact information
- Medical history
- Lifestyle details
The more accurate the information, the fewer disputes related to claims.
Not Understanding Waiting Periods
Most of the policyholders believe that coverage will start from day one for all types of disease they require treatment.
However, most policies have waiting periods for:
- Pre-existing diseases
- Specific illnesses
- Maternity benefits
During these waiting stages, claims may be denied
Policy Lapse Due to Non-Renewal
Failure to renew before the anniversary date could lead to policy expiration.
The insurer may deny the claim if a policy is inactive on the day you are hospitalized.
One way to avoid this mistake is by setting reminders to renew it.
Treatment Not Covered Under the Policy
Not every treatment is covered by every policy.
Some procedures may be excluded or have specific limitations.
Before hospitalization, review your policy coverage to understand what is included
Claiming During the Waiting Period
Also, even when a condition might be covered by the policy, claims may still be denied if they take place during the waiting period.
This is why it becomes crucial to understand the new policy timelines before buying a health insurance policy
Choosing a Non-Network Hospital Without Understanding the Process
A majority of policyholders take for granted that every hospital may support cashless claims.
However, cashless hospitalization is predominantly allowed in network hospitals.
The claim settlement process is subject to whether the treatment has been taken at a non-network hospital
Delayed Claim Intimation
Policyholders should typically notify insurers within a certain period of time following hospitalisation.
Claim notification delays are problematic.
Inform the insurer or claim support team at the earliest if you can.
Incomplete Documentation
Another reason claims get delayed or rejected is missing documentation.
Important documents may include:
- Hospital bills
- Discharge summary
- Medical reports
- Identity proof
- Claim forms
If you maintain proper records, it will ease the process.
Ignoring Policy Exclusions
However, every health insurance policy includes exclusions.
These are non-covered situations or treatments.
A lot of claims disputes happen as policyholders assume that all medical costs are included
Always review the exclusions section carefully.
Claiming Non-Medical Expenses
Some costs from hospitalization may not be covered.
Examples can include:
- Administrative charges
- Personal comfort items
- Certain consumables
Knowing what covered and non-covered expenses means helps to set the right mindset
Not Following Treatment Guidelines
At times, insurers will insist that treatment is designed to occur under certain policy terms.
Failure to meet these will impact claim approvals.
Always check guidelines before treatments are planned
Assuming Every Hospital Expense Is Covered
A policy may have limits on:
- Room rent
- Specific procedures
- Certain treatments
By reviewing policy limits ahead of time, claims settlement can lead to misunderstandings.
Depending Only on Employer Insurance
The majority of employees depend solely on their company’s health insurance coverage.
But that can vary when you leave a job or during retirement if you have employer-provided coverage.
Personal health insurance is more stable.
Not Reading the Policy Document
This is the most common mistake of all.
Many policyholders purchase insurance without reading the policy wording.
Understanding coverage, waiting periods, exclusions, and claim procedures before an emergency can help avoid future complications
What Insurance Advisors Usually Recommend
So what I suggest is that experience insurance advisers will say,
- Declaring all medical conditions honestly
- Understanding waiting periods
- Renewing policies on time
- Maintaining claim-related documents
- Reviewing exclusions carefully
- Seeking clarification before purchasing
That alone goes a long way in making the claim experience far more favorable.
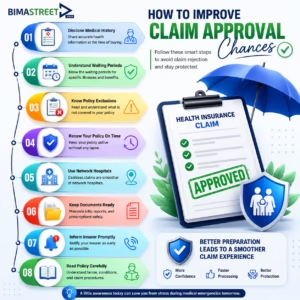
Quick Checklist to Avoid Claim Rejection
- Disclose medical history accurately
- Review waiting periods
- Understand policy exclusions
- Renew policy on time
- Use network hospitals whenever possible
- Keep medical documents safely
- Inform the insurer promptly
- Understand claim procedures
- Read the policy wording carefully
Conclusion
Health insurance claim rejection is a nightmare, especially when you are in the middle of a medical emergency.
But most claims issues could be avoided by making sure the terms of the policy are kept in mind and that common mistakes are not made
Transparency at the time of policy purchase, awareness of extent of coverage, adherence to claim procedures and some diligent documentation will help you continue towards a less troublesome claim experience.
At BimaStreet, we believe that informed policyholders make better insurance decisions.
Understanding these common mistakes today can help you avoid claim-related challenges tomorrow and make the most of your health insurance coverage