Health Insurance waiting period is one such factor that almost everyone remembers just before finalizing a policy, after letting go of an important opportunity.
Purchasing health insurance is the smartest thing anyone can do in their life but they lose out on essential elements like a waiting period?
Though your policy may be active the moment you actually pay for it, not every healthcare expenditure is covered from day one.
And as soon as their insurance is purchased, most policyholder tend to think that all of their hospitalisation expenses can be claimed
But for some illnesses, treatments and pre-existing diseases, there is a waiting period implemented during which time insurance companies do not cover the costs associated with that ailment
If you are not aware of these waiting periods, your claim might be delayed or even denied
Through this guide, you will understand everything regarding the Health Insurance Waiting Period, types of waiting periods,
why insurers keep them and how to find a policy that best meets your health requirements
What Is a Health Insurance Waiting Period?
Understanding the Basics
A Health Insurance Waiting period is the time you need to wait before making claims for certain diseases, treatments or medical problems under the health insurance policy
Your policy comes into effect the moment you pay the premium, yet certain claims do not become payable until after a specified waiting period
When you apply, there is a wait period which are based on:
- The insurance company
- The type of policy
- The illness or treatment
- Whether the condition is pre-existing
Awareness of these rules keeps you from getting an unpleasant surprise while settling a claim
Why Do Insurance Companies Have Waiting Periods?
Preventing Misuse of Insurance
Waiting periods help to minimize the chance that people will buy health insurance in response to a diagnosis or when they need urgent care,
as naturally these people would not be able to bring about a positive change in outcome outcome.
Waiting periods help insurers:
- Reduce fraudulent claims
- Maintain affordable premiums
- Justifiable coverage for all insured persons.
- Encourage long-term health insurance planning
These terms safeguard true policyholders and insurers
Types of Health Insurance Waiting Period
Initial Waiting Period
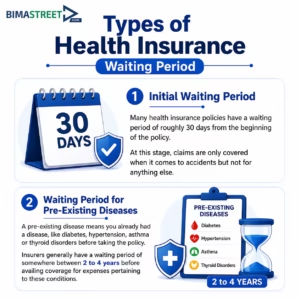
Many health insurance policies have a waiting period of roughly 30 days from the beginning of the policy.
At this stage, claims are only covered when it comes to accidents but not for anything else.
Waiting Period for Pre-Existing Diseases
A pre-existing disease means you already had a disease, like diabetes, hypertension, asthma or thyroid disorders before taking the policy
Insurers generally have a waiting period of somewhere between 2 to 4 years before availing coverage for expenses pertaining to these conditions.
Disease-Specific Waiting Period
There are specific waiting periods, irrespective of being pre-existing.
Examples include:
- Hernia
- Cataract
- Kidney stones
- Joint replacement
- Varicose veins
- Gallbladder surgery
There is normally a waiting time of 1 to 3 years for such conditions
Maternity Waiting Period
Health insurance plans that include maternity benefits usually have waiting periods ranging from 9 months to 4 years, depending on the insurer
Couples planning a family should purchase health insurance well in advance
What Happens During the Waiting Period?
Are Any Claims Allowed?
Yes. Most illnesses are excluded during the waiting period while accidental injuries usually receive immediate coverage once the policy starts, per terms of a policy
After the waiting period, routine illnesses will start to be covered.
Can You Reduce the Health Insurance Waiting Period?
Ways to Get Faster Coverage
Several insurers provide alternate methods to shorten the amount of waiting time, such as:
- Purchasing higher coverage plans
- Buying specific add-on covers
- Porting from another insurer with continuity benefit
- Maintaining uninterrupted policy renewals
Before making any decision, always compare policy policies
Common Mistakes Buyers Make
Avoid These Costly Errors
Common missteps among policy holders include:
- Not reading waiting period clauses
- Hiding pre-existing illnesses
- Buying insurance only after diagnosis
- Ignoring disease-specific waiting periods
- Not comparing waiting periods among insurers
Knowing these won’t lead to claims of regret.
Tips to Choose the Right Health Insurance Policy
Compare Before You Buy
Before purchasing health insurance, compare
- Waiting period duration
- Sum insured
- Premium
- Network hospitals
- Claim settlement ratio
- Day-care coverage
- Room rent limits
- Co-payment clauses
- Policy exclusions
Choosing the correct plan helps you to stay financially fit in a medical emergency
Frequently Asked Questions
Is every claim rejected during the waiting period?
No. Accidental hospitalization is covered from day one, whereas specialized illnesses can only be claimed after the waiting period has been fulfilled
Can waiting periods be waived?
Select insurers provide some waiting period concessions in the form of special plans or add-on benefits, but keep in mind that this is not a universal feature across all insurers.
Does every insurer have the same waiting period?
Yes, waiting periods are unique to each insurer and type of policy plan you choose
Conclusion
One of the most important things to do before buying any kind of health insurance policy, is to understand the health insurance waiting period
This feature helps you understand the waiting period for different medical conditions before your coverage is in effect, allowing surprises when the settlement of a claim
Choose insurance after carefully comparing the waiting periods, coverage, exclusions and claim settlement records of each policy instead of a decision being based only on premium
The earlier you buy health insurance, the better it is for you and your family, but continuing coverage ensures timely financial protection during times of a medical emergency
At BimaStreet, we believe that the right guidance is just as important as the right policy. When you understand what insurance advisors look for before recommending a plan, you’re in a much better position to choose health insurance that protects your family today and in the years ahead