When buying health insurance, many people tend to get confused with the sum insured and the premium
but miss out on an important detail of the policy, which is the room rent limit
The room rent is the amount charged by the hospital for the room that a patient is admitted to during the course of treatment
Some health insurance policies might have a cap on the daily room rent or a category of rooms that the policy covers
While some might cover the room rent without any restrictions up to the sum insured (subject to the policy terms)
A Health Insurance No Room Rent Limit can give the insured more flexibility in choosing a hospital room
But having no room rent limit does not automatically mean that all expenses during hospitalisation are covered.
Here is all you need to know about the room rent limit:
What Is a Room Rent Limit in Health Insurance?
Understanding the Sub-Limit
A room rent limit can be a restriction on the amount of room rent or a category of rooms that are eligible for coverage under a health insurance policy
For example, a policy might have:
- A fixed daily room rent limit.
- A percentage of the sum insured.
- A particular room category, such as a single private room
As per Rules, a sub-limit is a specific limit for various contingencies, treatments, services, or conditions.
In other words, the exact impact depends on the description in the policy document
What Does No Room Rent Limit Mean?
Greater Choice During Hospitalisation
As the name suggests, a policy with no room rent limit does not have a cap on the daily room rent
During hospitalisation, the insured can choose a hospital room as per their liking, subject to the policy’s applicable room category and other terms and conditions of the policy
But it does not mean that all expenses during hospitalisation would be covered.
Depending on the policy, the claim would still be subject to sum insured, exclusions, deductibles, co-pay, etc
Why Does the Room Rent Limit Matter?
Let’s say a policy has an explicit limit on the room rent, but the insured chooses a room category that costs more than the specified limit.
Depending on the wording of the policy, this could result in the insured having to bear
the difference and a proportionate reduction in some of the associated hospitalisation expenses
Some policy wordings explicitly mention a proportionate reduction if the room rent exceeds the specified limit.
This is why it is essential to read the policy document before buying a health insurance policy
What Are the Benefits of No Room Rent Restrictions?
More Flexibility in Choosing a Room
A policy with no room rent restriction can offer advantages such as:
- Greater choice of eligible hospital rooms.
- Reduced concern about exceeding a daily room-rent limit.
- Potentially simpler claim calculations relating to room rent.
- More flexibility during hospitalisation
The actual benefit depends on the individual policy wording
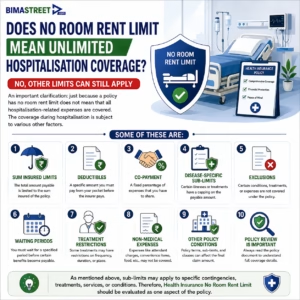
Does No Room Rent Limit Mean Unlimited Hospitalisation Coverage?
No, Other Limits Can Still Apply
just because a policy has no room rent limit does not mean that all hospitalisation-related expenses are covered.
The coverage during hospitalisation is subject to various other factors.
Some of these are:
- Sum insured limits.
- Deductibles.
- Co-payment.
- Disease-specific sub-limits.
- Exclusions.
- Waiting periods.
- Treatment restrictions.
- Non-medical expenses
As mentioned above, sub-limits may apply to specific contingencies, treatments, services, or conditions.
Therefore, Health Insurance No Room Rent Limit should be evaluated as one aspect of the policy
How to Compare Health Insurance Plans With No Room Rent Limit
Look Beyond This One Feature
While looking at the room rent limit is essential when comparing health insurance policies, there are several other important factors to consider:
- Sum insured.
- Room eligibility.
- Room rent restrictions.
- ICU coverage.
- Waiting periods.
- Pre-existing disease coverage.
- Co-payment.
- Deductibles.
- Network hospitals.
- Claim process.
- Exclusions.
A health insurance policy with no room rent limit can be beneficial, but the policy as a whole should meet one’s requirements.
Is a No Room Rent Limit Policy Worth Choosing?
Consider Your Healthcare Requirements
A health insurance policy without a room rent limit can be worth it if one wants greater choice during hospitalisation
Moreover, such a policy can be ideal for those who do not want to be restricted to a particular category of rooms during hospitalisation.
But the choice of a policy should depend on more than just the absence of a room rent limit
That would mean ignoring the premium and other terms and conditions of the policy.
After all, a higher premium should not be justified just because one does not have to worry about the room rent limit
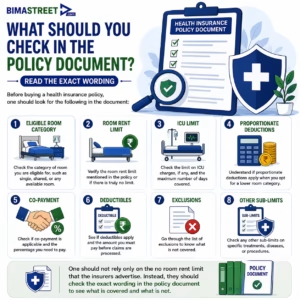
What Should You Check in the Policy Document?
Read the Exact Wording
Before buying a health insurance policy, one should look for the following in the document:
- Eligible room category.
- Room rent limit.
- ICU limit.
- Proportionate deductions.
- Co-payment.
- Deductibles.
- Exclusions.
- Other sub-limits
One should not rely only on the no room rent limit that the insurers advertise.
Instead, they should check the exact wording in the policy document to see what is covered and what is not.
Frequently Asked Questions
What is a no room rent limit health insurance policy?
It is a type of health insurance that does not have a restriction on the amount of room rent or a category of room that is eligible for coverage
Is no room rent limit better?
This feature can be beneficial but it is not the only factor to consider when comparing health insurance policies.
There are many other benefits, exclusions, deductibles, co-payment, etc. that one should consider
Can I choose any hospital room if there is no room rent limit?
Not necessarily; the policy might still prescribe a category of rooms that are eligible for coverage. So it is essential to check the wording of the document
Does no room rent limit mean the entire hospital bill will be covered?
No, the claim would still be subject to the sum insured, exclusions, deductibles, co-payment, waiting period, etc
Conclusion
Health insurance a No Room Rent Limit can provide greater flexibility during hospitalisation.
This means that one would not have to worry about the daily room rent limit during hospitalisation.
However, it is important to understand that this feature does not automatically mean that every expense during hospitalisation is covered.
It is essential to read the policy document to understand one’s rights and obligations under the policy.
Moreover, while comparing health insurance policies, it is vital to look at a wide range of factors beyond the room rent limit.
Sum insured, room eligibility, waiting period, co-payment, deductibles, network hospitals, claim process, exclusions, and other sub-limits are some of the features that one should consider while buying a health insurance policy.
Ultimately, a good health insurance policy would cover most of the expenses during hospitalisation without putting an undue strain on the finances.
Therefore, it is essential to look for a balanced policy that fits one’s healthcare requirements and financial capacity
At BimaStreet, we believe that the right guidance is just as important as the right policy. When you understand what insurance advisors look for before recommending a plan, you’re in a much better position to choose health insurance that protects your family today and in the years ahead